Wednesday, February 18, 2009

Tuesday, February 17, 2009
In the News: President Signs Economic Stimulus Measure

Today, we received news that President Obama signed the new $787 Million dollar stimulus package to "breathe new life into our economy," as stated by Ed Andrieski, a reporter for the Associated Press.
Here is something Realtors received today from the desk of Gary Wright, the 2009 President of the National Association of Realtors regarding the new Stimulus Package signed today by President Obama:
The $790 billion stimulus package signed by President Obama today increases the home buyer tax credit to $8,000, drops the repayment feature, reinstates last year's 2008 loan limits for FHA, Freddie Mac, and Fannie Mae loans, and provides $2 billion in additional funding for states and localities to be used to purchase, manage, repair and resell foreclosed and abandoned properties. Many elements (listed below) included in HR 1 "American Recovery and Reinvestment Act of 2009," were supported by the National Association of REALTORS® (NAR) as well as the many REALTORS® who sent call to action messages to Congress urging their support! Homebuyer Tax Credit.
The bill provides for a $8,000 tax credit that would be available to first-time home buyers (those who haven't owned in at least three years) for the purchase of a principal residence on or after January 1, 2009 and before December 1, 2009. The credit does not require repayment for buyers who hold onto their property for at least three years. Most of the mechanics of the credit will be the same as under the 2008 rules: the credit will be claimed on a tax return to reduce the purchaser's income tax liability. If any credit amount remains unused, then the unused amount will be refunded as a check to the purchaser.
NAR has sought removal of the repayment requirement because it discourages buyers from taking advantage of the tax credit. The three-year minimum holding period is a safeguard against speculators' use of the credit. The legislation also extends the effective date of the credit to December 1 from June 30, and extends eligibility to borrowers who buy their home with the help of state or local financial assistance that comes from the proceeds of tax-exempt mortgage revenue bonds.
The start date for the first time homebuyer credit is January 1, 2009 through and before December 1, 2009.
FHA and conforming loan limits. Specifics have not been released but reports indicate that the 2008 limits have been reinstated for 2009 except in those communities where the 2009 limits are higher. Additional increases in individual communities may also be available at the discretion of the secretary of the U.S. Department of Housing and Urban Development.
Foreclosure mitigation and neighborhood stabilization. Funding for states and localities to be used for neighborhood stabilization activities for the redevelopment of abandoned and foreclosed homes are authorized. Some news reports put the funding level at $2 billion.
Rental assistance. Up to $1.5 billion to provide short-term rental assistance and other aid for families during the economic crisis.
Transportation infrastructure. Up to $29 billion for highway construction projects, $8 billion for rail projects.
Rural housing development. Increased funding for the Rural Housing Service direct and guaranteed loan programs.
Low-income housing grants. Allow states to trade in a portion of their 2009 low-income housing tax credits for Treasury grants to finance the construction or acquisition and rehabilitation of low-income housing, including those with or without tax credit allocations.
Tax-exempt housing bonds. Tax-exempt interest earned on specified state and local bonds issued during 2009 and 2010 will not be subject to the Alternative Minimum Tax (AMT). In addition, financial institutions will have greater capacity to purchase tax-exempt state and local bonds.
Energy efficient housing. Grants for energy retrofits for federally assisted housing (Section 8), funding for energy efficiency and conservation block grants to states, increases in the residential tax credit through 2010 for certain energy efficient upgrades and $5 billion to weatherize low-income homes.
Greg Wright2009 PresidentWashington REALTORS®
Friday, February 13, 2009
An Announcement and a Word About Buyer Agency
On February 6th, 2009 I was awarded the Accredited Buyer's Representative designation (ABR) through the Real Estate Buyer's Agent Council. Although, this designation does not represent a committment to exclusive buyer agency. For me, earning this designation is a part of my personal committment to the exclusive representation of the buy-side of real estate transactions and to the advancement of exclusive buyer agency.
I should clarify that the practice of exclusive buyer agency is not the same as an agent who professes to be working exclusively for buyers, but who works for a real estate company that takes listings as well. A true exclusive buyers agent works for a broker and company that never takes listings because it has dedicated its entire business to representing the interests of buyers.
Exclusive buyer agency is an option that gives real estate buyers a way to completely avoid conflicts of interest in their real estate purchases, aka. "Dual Agency," and "Designated Agency," which is just another form of dual agency. Avoiding dual agency is especially valuable to investors because they rely on their real estate representatives to level with them and tell them when a listing is overpriced, as well as negotiate assertively on their behalf for a price that meets their investment objectives.
However, when a listing belongs to their agents' company or, worse, to their agent, the lines of loyalty can blur. In a dual or designated agency situation, a buyer cannot be 100% sure that their agent will tell them whether a listing is overpriced and by how much exactly. To do this would put them in direct conflict with their (or their brokers') duty to the seller.
With exclusive buyer agency, buyers can rest assured that the agent, broker, and company are representing their interests exclusively no matter what property they go to see. Buying real estate right is the first step to building a profitable portfolio of income properties. The peace of mind and degree of loyalty given by exclusive buyer agency is the value it brings to buyers whether buying a home or income property.
I believe the future will continue to be bright for exclusive buyer agency, and I will be working towards earning the Certified Exclusive Buyer's Agent (CEBA) designation through the National Association of Exclusive Buyer Agents (NAEBA), as well as the Certified Commercial Investment Member (CCIM) designation to better serve the acquisitions of my commercial and investment real estate clients. I strive for such excellence because I have a vested interest in the success of my clients. Their success is mine as well.
Real Estate Investing: Increase Your Financial Education
Whenever I talk to real estate investors who are just starting out on their journey to financial independence, I encourage them to build their knowledge through the many educational resources available that teach people how to build financial security in their lives.
My specialty is being an advocate for the buy-side of investment property purchase transactions for investor-clients. This has been a mission for me since 2003 when I became truly independent of the buyer/seller representation model of traditional real estate companies. Income property does not serve its intended purpose if it does not produce positive cash flow. The same can be said if the income produced does not meet an investors financial goals. Education is the key.
No matter who we are or where we come from, the road to creating financial security begins with obtaining good information, informing ourselves through the pursuit of financial education, and expanding our financial literacy. As a lifelong student of personal growth and development, I am always seeking out good educational resources to increase and expand my professional expertise and financial intelligence, as well as teach and share my experiences with the people I serve best...my valued clients, family, and friends.
Here is a video from the Rich Dad company with co-founder Robert T. Kiyosaki talking about three types of education. Enjoy!
Wednesday, January 21, 2009
King County Now Requires Septic Systems to be Inspected at Time of Sale

In the news recently, I found out that King County now requires all septic systems to be inspected at time of sale. Here is an excerpt from the bulletin issued by the Northwest Multiple Listing Service (NWMLS):
"January 16, 2009. In King County, the seller of any single or multi-family residential property served by an on-site septic system is now required to have a monitoring and performance inspection prior to transfer of title. King County will require the inspection and report to be completed by a King County licensed On-Site System Maintainer (OSM). A copy of the inspection report must be submitted to the Health Department and the buyer prior to transfer of title. The new requirement is set forth in King County Board of Health Code Section 13.60.030."
(Photo Courtesy: pottyon.com)
Here is in interesting factoid about septic systems from pottyon.com:
"Most septic systems are conventional systems that use gravity to distribute the effluent from the tank. When site conditions are not appropriate for a conventional system, other types of systems, such as low pressure distribution or mound systems are sometimes used.
Septic systems cannot dispose of all the material that enters the system. Solids that are not broken down by bacteria begin to accumulate in the septic tank and eventually need to be removed. The most common reason for system failure is not having these solids removed on a regular basis. When the holding tank is not pumped out frequently enough, the solids can enter the pipes leading to and from the tank. This can cause sewage to back up into the house or cause the drainage system to fail as the pipes and soil become congested. These problems are often costly to fix, pose a danger to public health, and are a significant source of water pollution. Seepage from inadequate or failing septic systems can contaminate both ground and surface waters. The industry recommends having a licensed company clean your septic tank every two years to perform preventative maintenance."
One thing I should note is that septic systems can be very costly to redesign and replace. According to Evergreen Septic Design, they can range anywhere from $5,000.00 to over $20,000.00 +. Therefore, regular maintenance is important. Some septic system companies recommend pumping the septic system every 2 to 3 years and others say every 5 years. I, personally, would err to the side of caution and do this every 2 to 3 years. The cost to do so is minimal and would be worth the money saved in having to redesign and install a completely new system.
I found a wealth of information about septic systems on Evergreen Septic Designs' website, so if you are interested in learning more about septic systems, this would be a good place to start. Other information resources include Amman Septic Designs Inc, and King County.
Monday, January 19, 2009
The Bust is a Boon: Buyers Across the US are Finding More Affordable Homes

From CNNMoney.com, the headlines read:
"From California to D.C., falling home prices and cheaper mortgage rates are making dream homes possible."
Yes, we are definitely in a buyers' market where homebuyers can find homes that were previously priced beyond their reach. This article from CNN features the stories of several buyers and their experiences in the current homebuying market. I thought this was an interesting article, so here it is.
Thursday, January 15, 2009
Some Things are Worth Second Chances: My Return to NAEBA

As of this week, I officially reinstated my company with NAEBA, or the National Association of Exclusive Buyer Agents. The change of heart came after a few years of going it alone with the encouragement of peers who were kind enough to keep in touch with me. After speaking with a few peers and Kim Kahl, who is the executive director of the organization I learned that many things have changed for the better. I am excited to see all of the new changes taking place, and I look forward to joining a committee and contributing my energy to the goals of the organization.

Wednesday, January 07, 2009
Sound Advice from a fellow EBA: How to Get The Best Deal in a Buyers Market

I came across a blog post today written by an EBA peer in Nashville entitled "Buying Real Estate - How to Get The Best Deal in a Buyers Market." The blog post presented some good and very helpful advice for buyers in today's buying environment, so I decided to blog about it and point the way! :)
Here is a sneak-peak:
"First and foremost...decide how you will pay for it! Do you have cash...or you will be looking for financing? If financing is in your plans...be sure to arrange for it ahead of time. Be sure to obtain a copy of your credit report and correct any mistakes...NOW! If you plan to live in the home as your primary residence, it will require a smaller down payment. But, if this is an investment...you should plan on at least 20% down. AND always have a pre-approval letter from your lender in hand when you make your offer! It will greatly help your agent negotiate the best possible price for you.
Then, when it's time to start house-hunting...look for a good Exclusive Buyer's Agent who will help you find the right property...and buy it at the best possible price. A few tips to consider when buying real estate..."
(photo: activerain.com)
Friday, January 02, 2009
Seven Fundamental Keys to Building Cash Flow in Real Estate

Whether a person invests in real estate, paper assets (like stocks and bonds), or business opportunities, investment strategies are unique to each individual. This blog will focus on one particular type of income producing asset--real estate. While there are many ways to build an investment strategy around real estate, for example, buying fixers and selling them for a profit or purchasing bare land and developing buildings for sale or lease-the scope of this article will focus on seven keys to building a strong portfolio of cash-flowing properties.
1. Assess Your Situation
(a) Know What You Need and Want
The first item to consider is whether real estate is right for you. It is not for everyone, but if you find that real estate investment is what you want, then designing a real estate investment plan is the best place to start. From a cash flow perspective, identify what your current monthly expense requirements are and how much income you need every month to maintain your current lifestyle. Once you have this figure, consider where you want to be in five, seven, or ten years, etc. How much monthly cash flow will it take to support this future goal? Then add this to your current monthly expense figure and you will have a starting point for your cash flow goals. This figure will most likely change as you begin working your plan and making periodic adjustments to your goals.
(b) Assess Your Direction and Identify Your Preferred Property Type
Within real estate, there are different property types from which to choose from, for example, single-family rentals, multifamily rentals, office buildings, industrial office buildings, warehouses or public storage, retail properties, etc. Each property type has its own unique considerations and operational requirements.
Researching and learning how to operate that particular property type means having the knowledge to manage the management team from an informed position.
(c) Know What Kind of Financing is Available
While the mortgage market recovers from its recent meltdown, financing requirements will remain tight, but there are still options available to facilitate purchases, such as seller financing and lease options. Learning about the different financing options available is a key factor in planning a real estate investment strategy. Financing can mean the difference between a good and bad deal. Before the mortgage crisis, lenders commonly required a 1.20 DCR or "debt coverage ratio"--meaning, they would require 20 dollars of income for every dollar of debt that the property carries. With this information and a property's net operating income, you can calculate maximum loan amounts and minimum equity requirements (aka. down payment) for any income producing property. This can also help determine whether a property is overpriced and at what price the property will yield your required rate of return.
(d) Set Your Required Rate of Return
If you want your money to work harder than a savings account or a CD, then determine your required rate of return upfront and use this rate to calculate the investment value of a property based on its net operating income. This maximum amount will be the point where you will draw the line on any particular investment. When a seller is not agreeable to your maximum price, then it is time to walk away and find an investment that will fulfill your investment requirements.
(e) A Word About the Tenant Landlord Law
If you are considering single-family and/or multifamily rentals, then you will need to become familiar, if not well versed, in Tenant Landlord Laws. Having a set system that keeps you in compliance with the law is a wise investment of time and money. Management companies and real estate attorneys can be helpful in this area.
2. Set Minimum Property Requirements and Limits
From a cash flow perspective, the ideal situation is to start receiving rents the following rent period after closing. If you have to gut and rehab a building entirely, there will surely be a period of downtime and you may have to support the property until you are able to lease and begin receiving income. If your goal is immediate cash flow, then a major rehab project may not be the right project type to consider. Instead, a well-maintained property or one that needs a minor amount of cosmetic work with a steady tenant history is the ideal property from a cash flow perspective.
3. Assemble a Stellar Team
Assembling a team of professionals dedicated to your financial success in real estate is a key component in realizing your cash flow goals.
The Real Estate Broker - A buyer's broker who is also an experienced investor, if you want to avoid dual agency, then find an exclusive buyer's broker to work with.
The Mortgage Planner - A mortgage planner that specializes in investment and commercial properties
The Financial Planner - A financial planner with a positive perspective towards-and a full understanding of-real estate investments
The Real Estate Attorney - To review all loan and closing documents before signing, as well as any contracts or agreements-this is a CYA (Cover Your Assets)
The Management Company - A professional management company with a solid reputation will free your time so you can live your life and look for more properties to buy
The Property Inspector - This team member should have experience inspecting your chosen property-type.
4. Real Estate Investments Are About the Numbers
Leave Emotions at Home
Buying a real estate investment is about making money with property-not falling in love with property. This is especially bad, if the seller becomes aware of the infatuation. Investment real estate is about what it can do to bring you closer to your income goals, period.
5. Buy Properties Right
List Price Does Not Set Property Value
Regardless of the price, you see on a listing, a property's investment value will vary between investors because his or her required rate of return will be unique to each situation. Therefore, a list price is just an asking price. Set your required rate of return and make an offer accordingly. If meant to be, the seller will either accept or open up negotiations. If not, then it will be better to walk away than to end up with a property that does not meet your investment goals.
6. Periodically Re-Assess Your Direction and Make Adjustments as Necessary
If you started out with single-family rentals, you may decide to upgrade and own small multifamily buildings. If you own small multifamily buildings, you may decide it is time to buy your first 16 or 20 unit building, etc. The point is to keep your eyes on the horizon for new opportunities to grow your knowledge and portfolio of income properties. With experience comes confidence and with confidence comes new learning opportunities that will continue on a path of limitless growth. When it comes to learning, growing, and evolving we limit ourselves by the barriers we place upon ourselves.
7. Cash Flow Strategy: Buy Right and Hold Long-term
The key to building cash flow through real estate investments is to buy properties that satisfy your investment requirements upfront and holding them for the long term--a minimum of five years or ideally ten years. Have an exit strategy in place before the property approaches the end of its holding period. Start learning about 1031 tax-deferred exchanges and speaking to a specialist who can help guide you through the process well in advance. Being familiar with the process will ensure a smooth exchange transaction and preserve your wealth-building strategy when the time comes. Your accountant, tax attorney, or a financial advisor well versed in the area of 1031 exchanges can provide you with more information.
In closing, real estate investing can be a very rewarding experience. It requires planning and knowledge, but the end-result can secure your financial future. Education and motivation are key factors in building wealth and achieving financial independence.
(photo: http://www.singlepointerealty.com/)
Tuesday, December 30, 2008
Buyers Agents Move Early To Stop Michigan's Designated Agency Bill

Buyer advocates in Michigan State are up in arms as they rally support from consumers and consumer advocate groups to stop their state from passing "voluntary designated agency" legislation. According to the article, the gist of this law is as follows:
The proposed law, according to the 26,000 + member Michigan Association of REALTORS® president Carol Frick, is designed to eliminate the inherent conflict of interest and confusion over who represents whom in the state's current dual agency statute, and would offer agents the ability to offer "exclusive" representation services under the supervision of their broker/managers.
There's the rub, say the dissenters. "There is nothing new for the consumer, there is no right to exclusive agency if the broker is assigning agents. Is the agent divorcing themselves from the company?" says Renee Knight, chairperson of Realdefenders. "That takes consumer rights away. They (consumers) think they are hiring the whole company when the other agents in the firm can be working against them."
Designated agency occurs when a home buyer is offered agency representation by the firm that is representing the seller of the same property. The firm designates one of its salespeople to act as the buyer's agent and another as the seller's agent, explains a NAEBA release.
Whether buying or selling real estate, consumers need to have options in the market to protect and maintain their interests--especially, since a real estate transaction is a significant life-event and financial investment. Consumers deserve to have the assurance that their agent works exclusively for them and that their agents' company stands behind their agents work 100% without the added conflict of competing interests that is unavoidable with dual or designated agency.
Thursday, December 25, 2008
Dual and Designated Agency: A Picture is Worth a Thousand Words

A friend on MySpace found this awesome picture that does a great job illustrating what dual and designated agency is and why they are both a conflict of interest. This picture is definitely worth a thousand words.
Dual agency happens when one agent represents both buyer and seller in the same transaction or when one company assigns two different agents within their company to represent buyer and seller respectively in the same transaction. The effect of designated agency is the same as dual agency because the same broker (company) is "designating" two agents from his or her company to represent buyer and seller respectively in the same transaction. The effect is the all the same. It's dual agency no matter how you color it up. The cartoon above illustrates the effect of dual / designated agency loud and clear.
Merry Christmas to all!
Tuesday, December 23, 2008
SNOW: And We Thought We Had it Bad
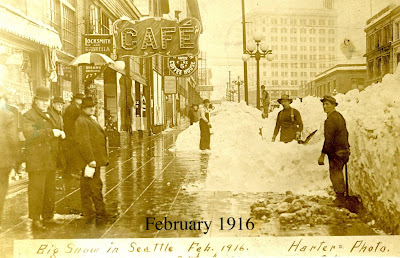
This morning, I was working on my profile (MySpace) and I saw a bulletin posted by a friend that made me feel a little better about the heavy snow we've been having here lately. We thought we had it pretty bad these past few days, but when I saw this photo, it made me appreciate just how bad things could get. Thank goodness we didn't get it this bad. Thanks for the photo, Laurie! :)
Friday, December 19, 2008
New HUD Online Resource: My Money, My Home, My Future

I received news today about a new online resource presented by HUD called, "My Money, My Home, My Future." As I visited the site, I found the following brief description:
"The Department of Housing and Urban Development emphasizes that healthy homeownership depends on a strong foundation of financial knowledge and enables the long-term social, emotional and financial stability of families."
The website centers itself on educating the public about getting ones financial house in order starting with (1) Building a financial foundation (2) Sustaining healthy homeownership, and (3) Achieving financial security.
There seems to be many positive resources emerging in these volitile times. This is all very encouraging to me.
Thursday, December 18, 2008
Fed Action Creates Best Interest Rates in 50 Years, Realtors(R) Report

Just received a news alert about a new Realtor Report regarding how action by the Fed is creating best interest rates in 50 years:
"WASHINGTON, Dec 17, 2008 /PRNewswire via COMTEX/ -- The National Association of Realtors(R) applauds the actions of the Federal Reserve Board in lowering interest rates for home buyers and homeowners who need to refinance. This will significantly impact housing sales, home valuations, and the nation's overall economy" (National Association of Realtors)
(photo: hullstudent.com)
Avoiding Foreclosure: New Online Resource by Freddie Mac

Today, I found out about a new online resource center dedicated to the prevention of foreclosures presented by Freddie Mac. As I visited the homepage of this new resource center, I read about Freddie Mac's commitment to helping borrowers to avoid foreclosure and to keep them in their homes whenever possible. According to the website, the resource center provides a one-stop shop for those who interface with consumers - especially the Sellers, Servicers, and community-based organizations working in neighborhoods every day that are helping homeowners avoid foreclosure. Despite the recent troubles Freddie Mac has been facing, it is good to know that they are doing what they can to help homeowners stay in their homes.
The most notable thing I read was their announcement made on November 20, 2008 of their 6-week suspension of all foreclosure sales and scheduled evictions on occupied single family 1-4 unit residences with Freddie Mac-owned mortgages beginning November 26, 2008 through January 9, 2009. Here is a link to the new resource center presented by Freddie Mac:
(photo: banks.com)
Monday, December 15, 2008
New Low Mortgage Rates May be Out of Reach for Some Buyers!

New lower mortgage rates are out of reach for many buyers because of new stringent qualifying requirements. In a December 3rd article by David M. Dickson, a writer for the Washington Times discusses significantly tighter credit standards, new qualification criteria, and how mortgage rates dramatically dropped after the Fed announced its plan to "spend $600 billion dollars to purchase debt and mortgage-backed securities guaranteed by Fannie Mae, Freddie Mac and Ginnie Mae" (Dickson).
To read entire article, click here: Mortgage Rates May be Out of Reach for Some Buyers
Monday, October 20, 2008
FHA Improvements Allow Buyers to Qualify for Mortgages Using Non-Traditional Credit Building
For many years, the issue of building credit was always a mysterious topic that not many people could understand. It used to require the assumption of debt in order to build a strong credit file over time. With the new improvements to FHA, buyers can now build positive credit files with payments made to basic everyday bills like utility payments or any other type of monthly bill--not just credit cards, mortgages, or any other bill related to the repayment of debt. By enrolling in the "Payment Reporting Builds Credit" program, buyers can establish or re-establish their credit within 12 months.
Read more info about this refreshing new program:
Payment Reporting Builds Credit
More information about the new FHA Improvements
Monday, September 08, 2008
Feds Bail Out Fannie Mae and Freddie Mac
Just an hour ago, Malden Read, a reporter for the Washington Post, annoucned that the Feds are bailing out Fannie Mae and Freddie Mac. According to Read, this move by the Feds, "could aid a recovery of the broken U.S. housing market and arrest a slide in stock and credit markets worldwide."
Read the full story:
http://www.washingtonpost.com/wp-dyn/content/article/2008/09/08/AR2008090800542.html
Thursday, August 14, 2008
How to negotiate your closing costs
Shop around before choosing a mortgage lender, but don't stop there. When you receive your good faith estimate of closing costs, or GFE, the negotiation hasn't ended.
Excerpt from "How to Negotiate Your Closing Costs" by Holden Lewis of BankRate.com:
The lender or mortgage broker is required to give you a GFE within three working days of accepting your loan application. The GFE comes in the form of an itemized list of estimated closing costs for everything from the lender's fees to the appraisal charge to the title insurance premium to a partial month's interest payment.
The lender or broker charges some fees, and third parties charge others. The first step is to find out which are loan origination fees and which are third-party fees. Don't guess. Ask the lender or broker.
The big money question"Say, 'Please explain to me what those fees are,'" says Jessica Cecere, director of the Consumer Credit Counseling Service in West Palm Beach, Fla.
Simple advice, but a lot of loan applicants don't follow it.
On the GFE, fees are categorized by numerical codes ranging from the 800s to the 1300s. Most of the negotiable lender-charged fees are in the 800s: application, origination, commitment, loan discount, broker, tax-related service and underwriting fees.
Read full article on BankRate.com
Sunday, July 06, 2008
What Buyers Need to Know About the New Distressed Properties Law
According to Washington State Attorney General Rob McKenna, the original draft of the controversial Distressed Properties Law intended to protect homeowners from equity skimming scam artists. It was originally very narrow in scope and specifically targeted certain individuals who promise aid to distressed homeowners, but who would end up stealing a distressed home owner's equity.
The original intent of this law was well-meaning when it was first drafted, however, when the draft reached the State senate, the senate added new language at the last minute that made the law very broad and harmful not only to Realtors, but also to buyers. Steps are being made to correct the harmful language of this new law. However, until then, buyers and their agents must take care to avoid the actions that would impose the "Distressed Home Consultant" designation upon them.
What buyers and their agents need to watch out for:
1. Do not make any offers to save a home from foreclosure
2. Do not contact lenders on behalf of the seller (buyers and their agents should not be doing this anyway)
3. Do not close (or set a closing date) within 20 Days of a scheduled foreclosure date (IMPORTANT)
4. Do not systematically contact distressed homeowners, for example, looking specifically for foreclosure properties to buy, etc.
What happens if a buyer and/or their agent becomes a "Distressed Property Home Consultant"
1. Under the new law, if the "Distressed Property Home Consultant" designation is imposed, buyers and their agents will owe fiduciary duties to distressed homeowners under consumer protection laws. There will also be cumbersome procedures that must be followed under this legal implication (see video below for more details). This is a bad situation for buyers to be in, as well as their agents. At this point, buyer's and their agents would need to consult with their respective legal advisers asap.
It is critical to understand that distressed property homeowners cannot waive their rights under this new law. Therefore, the best way to avoid the risk of implication is to avoid being exposed to this situation altogether.
Bottom line:
Until legislative officials remove or revises the adverse language contained in this new law, buyers and their agents will need to stay vigilant and aware--being very careful not to become ensnared in the flaws of this new law.
To learn more about this new law and find out what is being done about it, watch this video as Washington Attorney General Rob McKenna discusses the issue:
The Distressed Property Law: Next Steps & Solutions
To learn more about this law in general as well as its implications, watch this video produced by the Washington Association of Realtors, Northwest Multiple Listing Services, and supported by the Washington State Department of Licensing:
Distressed Properties DVD Chapter 1
For buyers contemplating the purchase of a residential property of 1-4 units or who have questions about this law, please consult with your attorney and be clear on how to proceed with your buyer's agent before stepping into the market. Preparation and planning will go a long way to prevent becoming a "Distressed Property Consultant."
Subscribe to:
Posts (Atom)


